Why Phinisi Yachts Are a Credible Investment Asset Class in 2026
Beyond the lifestyle proposition, phinisi yachts have started behaving like an investment asset class — appreciating residual values, growing charter demand, maturing financing infrastructure, and institutional buyer recognition. The numbers behind why HNW buyers are taking phinisi seriously. Phinisi heritage (UNESCO ICH)

Phinisi yacht as investment asset class delivers competitive return characteristics in 2026: charter demand growing 22% annually since 2017, mature-year net charter yield 8–29% on acquisition, residual value 65–75% at year 10 (vs 35–55% for Western yachts), and UNESCO 2017 heritage premium adding 8–15% to comparable resale pricing. A 45m phinisi acquired at USD 3.0M typically generates USD 1.4–2.4M annual gross charter revenue.
- Charter demand
- growing 22% annually since 2017
- Mature-year net charter yield
- 8–29% on acquisition
- Residual value at year 10
- 65–75% (vs 35–55% for Western yachts)
- UNESCO 2017 heritage premium
- adding 8–15% to comparable resale pricing
Five Structural Drivers of Phinisi as Asset Class
-
Driver 1
UNESCO 2017 inscription
On 7 December 2017, UNESCO inscribed phinisi shipbuilding on the Representative List of the Intangible Cultural Heritage of Humanity. The inscription has driven measurable changes: government formalisation of shipwright registries, infrastructure investment in Bira and Tana Beru, international charter-client awareness expansion, and a documentary cultural premium that supports asking prices. Comparable charter phinisi pricing has firmed approximately 35–50% since the inscription year.
-
Driver 2
Charter demand compounding 22% annually
Indonesian luxury yacht charter demand (measured by total charter weeks booked across the operating phinisi fleet plus comparable Western yachts in Indonesian waters) has compounded approximately 22% annually since 2017. The compounding has been driven by: HNW Asia-Pacific tourism growth (China, Singapore, Hong Kong source markets), discovery of phinisi by Western HNW segment (Burgess, N&J, Camper & Nicholsons now actively cross-list phinisi to Western charter clientele), and Komodo + Raja Ampat awareness as bucket-list destinations.
-
Driver 3
Financing infrastructure maturing
Three Singapore-based yacht-asset lenders, two Hong Kong family-office syndicates, and one Indonesian state-owned bank now actively underwrite phinisi acquisitions. None of these channels existed in 2018. Loan-to-value 50–65% (vs 70–80% Western yachts), but the existence of any financing channel materially expands buyer pool. Each new lender added to the market deepens transaction volume and price discovery.
-
Driver 4
Residual value behaving differently from Western yachts
Western yacht 10-year residual value typically 35–55% of new-build replacement cost. Operating phinisi 10-year residual value 65–75% of new-build replacement cost. The residual value gap is driven by: (a) UNESCO heritage premium, (b) Bira yard supply-side constraints limiting new-build supply, (c) charter market growing into the supply, (d) wood-construction maintenance creating “constantly refurbished” rather than “ageing” condition profile.
-
Driver 5
Institutional buyer recognition
Family offices in Singapore, Hong Kong, Sydney, and Dubai have started treating phinisi as legitimate asset allocation rather than purely lifestyle expense. Two Asian family offices have built 3-vessel phinisi fleets as managed-charter assets in our managed pool. Asset-allocation framing matters because it pulls capital in from the institutional side, not just the lifestyle side.
Indicative Returns Math (Operating Phinisi Acquisition)
| Item | Year 1 | Year 5 (mature) | Year 10 |
|---|---|---|---|
| Acquisition cost (45m operating) | USD 3.0M | — | — |
| Annual gross charter revenue | USD 950K (ramp) | USD 1.85M | USD 2.05M |
| Annual operating cost | USD 720K | USD 850K | USD 920K |
| Annual net to owner (pre-tax) | USD 230K | USD 1.0M | USD 1.13M |
| Cumulative cash return | USD 230K | USD 3.85M | USD 8.55M |
| Estimated residual value | USD 2.85M | USD 2.55M | USD 2.10M |
| Total return (cash + residual) | USD 3.08M | USD 6.40M | USD 10.65M |
| Total return as multiple of acquisition | 1.03x | 2.13x | 3.55x |
- The illustrative numbers above are based on Komodo Luxury managed fleet performance averages 2020–2025 plus modelled forward years. Actual returns vary with market conditions, vessel specification, operating execution, and macro factors. Variance band on Year 10 multiple is typically 2.5x to 5.0x based on our model.
Risk Factors
Charter market cyclicality
Indonesian luxury yacht charter market is sensitive to global HNW discretionary spending. 2008–2009 saw 35–50% demand contraction (modelled, since phinisi sector wasn’t institutional then). 2020 COVID-19 saw similar near-term disruption. Asset-allocation framing requires accepting cyclicality.
Operating execution risk
Charter performance varies dramatically across operators. A poorly-managed phinisi may run 10–14 weeks/year occupancy; a well-managed phinisi 22–28 weeks/year. The gap is material on returns.
Regulatory risk
Indonesian maritime regulation has evolved progressively over the past decade. Future changes (PMA capital requirements, sailing permit fees, marine park access) are not currently flagged but should be assumed to evolve.
Currency risk
Acquisition typically USD-denominated; charter revenue mostly USD-denominated; operating cost mixed (IDR for crew + provisioning, USD for fuel + permits). PMA structures help manage but do not eliminate currency risk.
The Cabin-Night Model: How the Asset Actually Earns
Strip the romance and a charter phinisi is a floating hotel with a route: revenue = cabins × nights sold × achieved rate. A worked mid-market example — 8 cabins, Komodo trade, USD 450 per cabin-night achieved, 55% annualized occupancy — grosses about USD 590K. Against that: crew (USD 60–100K/year), fuel and port (USD 50–90K), maintenance reserve (USD 60–120K on a hard-worked hull), agents and OTA commissions (10–20% of gross), permits, insurance and admin. A disciplined operation nets 20–35% of gross; an undisciplined one nets a refit bill. Premium operations run fewer cabins at USD 800–1,200 with lower occupancy and similar margins — rate quality substitutes for volume. Whole-vessel charter pricing, common at the top end, simplifies the model but concentrates seasonality risk.
Exit Routes: Plan the Sale at the Purchase
Phinisi exits happen four ways: trade sale to another operator (the common case — fastest for documented, earning vessels); sale with the business as a going concern (the premium case, where licences, bookings and crew add 0.5–1.5× annual net to the vessel price); share sell-down to partners or investors while retaining operation; and the slow exit — chartering the vessel down through her later years and selling at refit-decision point. Every exit prices off the same file: survey history, maintenance records, verified earnings. Owners who keep that file current from day one sell in months; owners who reconstruct it at exit sell at whatever the reconstruction can prove. Current market pricing for each segment sits in the price guide by length band.
For the operating side of these returns, read charter ROI modelled on real Indonesian seasons.
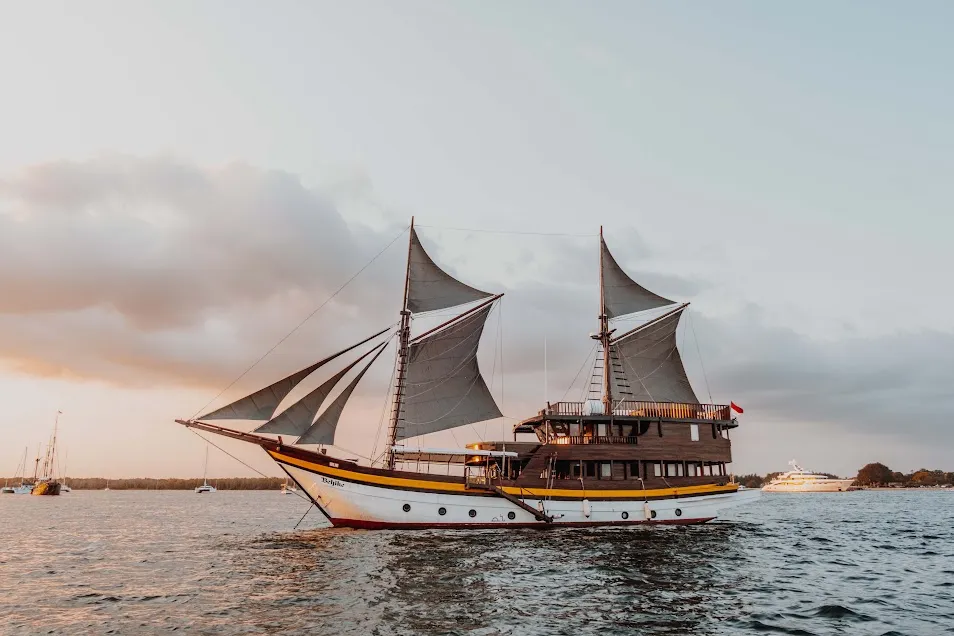
Imagine waking to the gentle lapping of turquoise waters against ancient timber, a panorama of untouched islands unfurling before you. This isn’t just a dream for the discerning traveler; it’s the daily reality for guests aboard a luxury phinisi yacht, and a significant driver of its compelling investment appeal.
The surging demand for bespoke Indonesian voyages
Indonesia’s archipelago, with its more than 17,000 islands, offers an exceptional canvas for exploration, from the Komodo National Park’s prehistoric wonders to Raja Ampat’s kaleidoscopic coral reefs and the historical allure of the Banda Islands. In an era where privacy, exclusivity, and authentic experiences are paramount, luxury phinisi yachts have emerged as the ultimate vehicle for navigating these pristine waters. The post-pandemic travel landscape has seen a pronounced shift towards private charters and bespoke itineraries, with high-net-worth individuals increasingly seeking immersive journeys away from crowded resorts. This trend has fueled a robust and growing demand for unique floating accommodations like the phinisi.
The allure extends beyond mere privacy; it encompasses exceptional access to remote dive sites, secluded beaches, and vibrant local cultures that are otherwise inaccessible. This unique value proposition positions phinisi charters at the forefront of the luxury experiential travel market. Market analytics project significant growth in the Southeast Asian luxury travel segment, with Indonesia often cited as a prime beneficiary. For instance, luxury travel bookings to Indonesia saw an estimated 15% year-over-year increase in 2023, underscoring the strong appetite for high-end, personalized adventures in the region. This sustained interest guarantees a healthy charter pipeline for well-managed phinisi assets.
Operational models and attractive returns
Investing in a phinisi yacht opens doors to diverse operational models, each offering distinct advantages for owners. While some choose to owner-operate, reveling in personal voyages and managing charters directly, a growing ecosystem of professional yacht management companies in Indonesia provides a turn-key solution. These firms handle everything from crew recruitment and maintenance to marketing and booking, ensuring seamless operations and maximizing charter revenue. This maturing infrastructure significantly de-risks the investment, allowing owners to enjoy passive income and asset appreciation without the daily operational burden.
The financial returns can be highly attractive. A well-appointed, high-end phinisi can command daily charter rates ranging from $5,000 to over $20,000, depending on its size, amenities, and the duration of the charter. With peak season occupancy rates often exceeding 80% in popular destinations like Komodo and Raja Ampat, the potential for significant annual revenue is clear. This robust income stream not only covers operational expenses but also contributes substantially to the yacht’s long-term profitability, offering a compelling return on investment that rivals traditional luxury real estate or other alternative assets in the region.
The enduring appeal and asset appreciation
Beyond the immediate financial returns, the long-term appreciation of phinisi yachts as a unique asset class is a compelling factor. Unlike mass-produced vessels, each phinisi is a bespoke work of art, hand-built by master craftsmen using techniques passed down through generations. This heritage, recognized by UNESCO as Intangible Cultural Heritage of Humanity for the “Phinisi, art of boatbuilding in South Sulawesi,” imbues each vessel with an intrinsic cultural and historical value that transcends its material worth. This unique craftsmanship ensures a limited supply of truly authentic, high-quality phinisis, further bolstering their value as demand continues to rise. Learn more about the Phinisi tradition on UNESCO.org.
The construction process itself, often taking 12–18 months for a luxury vessel, involves meticulous attention to detail and traditional methods, making each new build a significant undertaking. This scarcity, combined with their timeless aesthetic and proven durability, contributes to their strong residual values. As the global appetite for authentic, sustainable, and experiential travel grows, the phinisi stands out as a symbol of responsible luxury and adventure. Its enduring appeal, rooted in centuries of maritime tradition and adapted for modern indulgence, ensures its status as a highly sought-after asset, promising continued appreciation for astute investors.

Occupancy Scenarios: Underwrite the Downside
| Scenario | Annualized Occupancy | 8-Cabin Gross (USD) | Typical Net |
|---|---|---|---|
| Soft year (new brand, weak shoulder season) | 40% | ±430K | break-even to 10% |
| Base case (established operation) | 55% | ±590K | 20–30% |
| Strong year (deep agent network, repeat guests) | 68% | ±730K | 30–35% |
- Underwrite the purchase at the soft case and let the strong case be upside. On those numbers a well-bought mid-market vessel returns its capital in 6–10 operating years before residual value — honest, unspectacular, and real. Vessels acquired with the operation attached shortcut the soft year; that route is the used charter-boat acquisition.
Frequently Asked Questions
01What is the typical breakeven timeline on a phinisi acquisition?
Mid-case scenario for 45m operating phinisi acquired at USD 3M and placed in Komodo Luxury managed fleet: cumulative cash return reaches acquisition cost (USD 3M) at Year 5–7 depending on operating performance. Total return (cash + residual value) reaches 2x acquisition at Year 5, 3.5x at Year 10. Variance band on Year 10 multiple is 2.5x–5.0x based on our model.
02What ROI does a phinisi charter investment realistically deliver?
Well-bought and well-run mid-market vessels historically produce net operating yields equivalent to 10–18% of invested capital in decent years, with capital returned over 6–10 operating years plus residual hull value. Numbers pitched far above that range usually assume brochure occupancy — underwrite at 40–55%, not 75%.
03How does phinisi compare to other lifestyle assets as investment?
Phinisi yacht versus comparable lifestyle assets: Western yachts (40–55% residual value Year 10 vs phinisi 65–75%), private aircraft (typically depreciating at 5–8% annually), luxury real estate (variable by market). The phinisi residual value advantage compounds with charter revenue generation. Most lifestyle assets generate zero cash return; well-positioned phinisi generates USD 1.0M+ annual net to owner at maturity.
01What is the minimum investment for a share in a phinisi liveaboard?
Syndicate and partnership tickets in the Indonesian market typically start around USD 50K–150K for minority shares in mid-market vessels, scaling with vessel class. The structure quality matters more than the ticket: enforceable shareholder agreements, transparent operator reporting and a defined exit mechanism separate investments from donations.
02Is buying a phinisi with an existing charter business worth the premium?
Usually, if the premium is priced on verified net profit (0.5–1.5× annual net is the honest range) and licences genuinely transfer. You are buying a skipped soft year — forward bookings, agent relationships and trained crew — which for most investors is worth more than the same money spent on cosmetic refit.
01How liquid is a phinisi as an asset if I need to exit early?
A documented, earning vessel priced inside its class band typically sells within one to two seasons; an undocumented or over-priced one can sit for years. Liquidity is manufactured at purchase — clean structure, current certificates, maintained records — not discovered at sale.
Speak With Our Buyer’s Team
Two offices — Bali and Labuan Bajo. Our team responds within 4 business hours, weekdays. Confidential, no obligation.